Is a vzw liable for VAT? The bar, your events and the exemptions

Status on 29 October 2026: the rules below are checked against the FOD Financiën page on VAT for vzw's and the FOD pages it links to.
A vzw is liable for VAT as soon as it regularly sells goods or services, with or without a profit motive. Its legal form changes nothing.
Many vzw's still charge no VAT on their main activity. It's exempt under article 44 of the VAT Code, or their taxable sales stay under the small business threshold.
Our advice: look at each activity of your vzw separately and give each its own price list. Then your accountant can check the status per activity.
- VAT status follows the activity, not your vzw's legal form.
- Sport for members can be exempt; the bar or canteen never is by itself.
- An occasional fundraising dinner or party of an exempt vzw can be exempt (article 44, § 2, 12°).
- Up to €25,000 taxable sales a year, the small business exemption can apply, unless you must use a registered till.
- Peppol also applies to a vzw with a VAT number or under the small business exemption.
When is a vzw liable for VAT, and when not?
A vzw becomes a VAT payer through what it does, not through what it is. Three positions are possible.
- It sells nothing. A vzw that only receives donations isn't a VAT payer and needs no VAT number.
- It only does exempt work. Sport for its members, theatre, education or care, for example. It charges no VAT and can't deduct any.
- It sells taxable goods or services. A bar, a shop, advertising for sponsors. Then it's a VAT payer for those sales.
Most clubs sit in two positions at once. The sport is exempt, the bar isn't.
The FOD page on who is a VAT payer calls that charging VAT "only on the taxable activities".
In 30 minutes we'll show you how to give every activity of your vzw its own price list and report, ready for your accountant.
What VAT status does each activity of your vzw have?
Look up each activity separately. Its VAT status follows the activity, not the club.
| Activity | VAT status | Source |
|---|---|---|
| Donations only, nothing sold in return | outside VAT, no VAT number | FOD vzw page |
| Sport for members at a non-profit sports club | exempt (art. 44, § 2, 3°) | GKS guidelines, example |
| Club bar or canteen open to visitors | taxable | GKS guidelines, example |
| Yearly fundraising dinner of an exempt vzw, proceeds only for its exempt work | exempt (art. 44, § 2, 12°) | GKS guidelines, example |
| The same dinner, by a vzw whose work isn't exempt | taxable | art. 44, § 2, 12° (list of exempt bodies) |
| A party or dinner so frequent it becomes a main activity | taxable | FOD vzw page |
| Canteen with more than the GKS threshold in served food | taxable, registered till required | GKS guidelines |
Running a youth movement or youth house? Article 12° only covers bodies whose own work is exempt under the points it lists.
Whether yours qualifies depends on what it does. Check that with your accountant before you count on the exemption for a party.
Is a vzw's bar exempt from VAT?
No. Selling drinks and snacks to visitors is a normal taxable activity, also inside an exempt sports club.
The FOD's own example says so in two words: canteen "not exempt".
So a club with a busy canteen checks two things. Which VAT rates apply to what it sells? And does its turnover stay under the small business threshold?
The rates are the same as in any café or at any event. Our guide on VAT on drinks and food at events lists them per situation.
When is a fundraising dinner or party exempt?
A fundraising event is exempt under article 44, § 2, 12° when an exempt vzw organises it only for its own benefit. Four conditions must all hold:
- The vzw's own work is exempt under one of the points article 12° lists (sport, social work and youth care, education and a few other points).
- The vzw organises the event itself, and the proceeds go only to that exempt work.
- The exemption doesn't distort competition with businesses that do the same.
- It stays occasional. Events may not be so frequent that they become a main activity.
The FOD's guidelines for the registered cash register work it out for a sports vzw: its yearly mussel festival brings in €45,000 and is exempt.
So the festival needs no registered till and no receipts. The same club's canteen stays taxable all year. That's why the two need separate figures.
How does the €25,000 small business exemption work?
A vzw with taxable sales of at most €25,000 a year, excluding VAT, can use the small business exemption scheme of FOD Financiën.
It then charges no VAT and files no periodic VAT returns. What comes with it:
- No deduction: VAT on the beer you buy stays a cost.
- An annual client listing: by 31 March, with last year's turnover, or zero.
- Invoicing and bookkeeping: some duties stay.
Does your exempt sport count towards the threshold?
No. The turnover that counts leaves out "de handelingen die worden vrijgesteld krachtens artikel 44, §§ 1 en 2".
Do watch the threshold during the year. Go over it by at most a tenth and you lose the exemption from the next calendar year.
Go over it by more, and VAT applies from the sale that crossed the line.
What's the catch?
The scheme is closed to small businesses that must use a registered cash register. A canteen that serves more than the GKS threshold in food each year is out.
Beyond Ordering is certified as a GKS 2.0 supplier, for the clubs that cross that line.
Does a vzw need a VAT number and Peppol?
Whether you need a VAT number depends on the position above.
| Position of your vzw | VAT number | Periodic VAT returns |
|---|---|---|
| Sells nothing, only donations | no | no |
| Only exempt activities (article 44) | no, unless it buys goods or services from another EU country (in some cases) | no |
| Taxable sales under the small business exemption | yes, under the scheme | no periodic returns; an annual client listing |
| Taxable sales, normal scheme | yes | yes, periodic returns, with deduction |
E-invoicing through Peppol has been mandatory since 1 January 2026 between Belgian businesses that are VAT payers, according to efactuur.belgium.be.
For a vzw, the official FAQ on who must e-invoice gives three cases:
- Under the small business exemption: Peppol applies to you too.
- With an active VAT number: Peppol applies.
- Only article 44 exempt work: you needn't send or receive structured e-invoices.
A vzw that sells nothing and only receives donations isn't a VAT payer, so the obligation doesn't touch it.
How do you keep the activities apart on the day?
Keep every activity on its own price list. Then each one has its own turnover, and your accountant can treat it the right way. In practice, for a club:
- The canteen: on its own price list, with the VAT rate on every product.
- The fundraising dinner: on a separate list and report, so its proceeds are visible on their own.
- Volunteer and crew drinks: as internal credits, kept out of your turnover.
Your dinner's report is the figure your accountant needs to check the article 44 exemption.
In Beyond Ordering all those price lists sit in one back office, as at Muziekclub N9 below.
The greatest asset of Beyond Ordering is its immense flexibility. We maintain stable operations in our music club, but for our summer events, we scale up in a heartbeat by renting exactly the extra hardware we need. No unnecessary overkill or costs in the winter, just maximum capacity and speed when we're going all out outdoors in the summer.
In practice: Muziekclub N9
The event: Muziekclub N9 runs club concerts in its own concert hall through the season, and large outdoor summer events such as Helden in het Park.
The challenge: the club is run by the vzw Driewerf Hoera (KBO 0419.303.977), which has been registered for VAT since 2020. The hall and the summer events need very different setups.
The setup: in the club, a small fixed set of all-in-one terminals takes card and contactless payments. For the summer events, N9 rents extra mobile terminals and adds deposits and cash cards.
Staff credits run through QR vouchers. Every sale and price list sits in the same back office, for a concert in the hall or a festival in the park.
The result: volunteers and bar staff use the same screens in winter and summer.
For VAT, the point is the separation. Staff spend through QR vouchers, a payment method of their own, so your accountant can see that line apart.
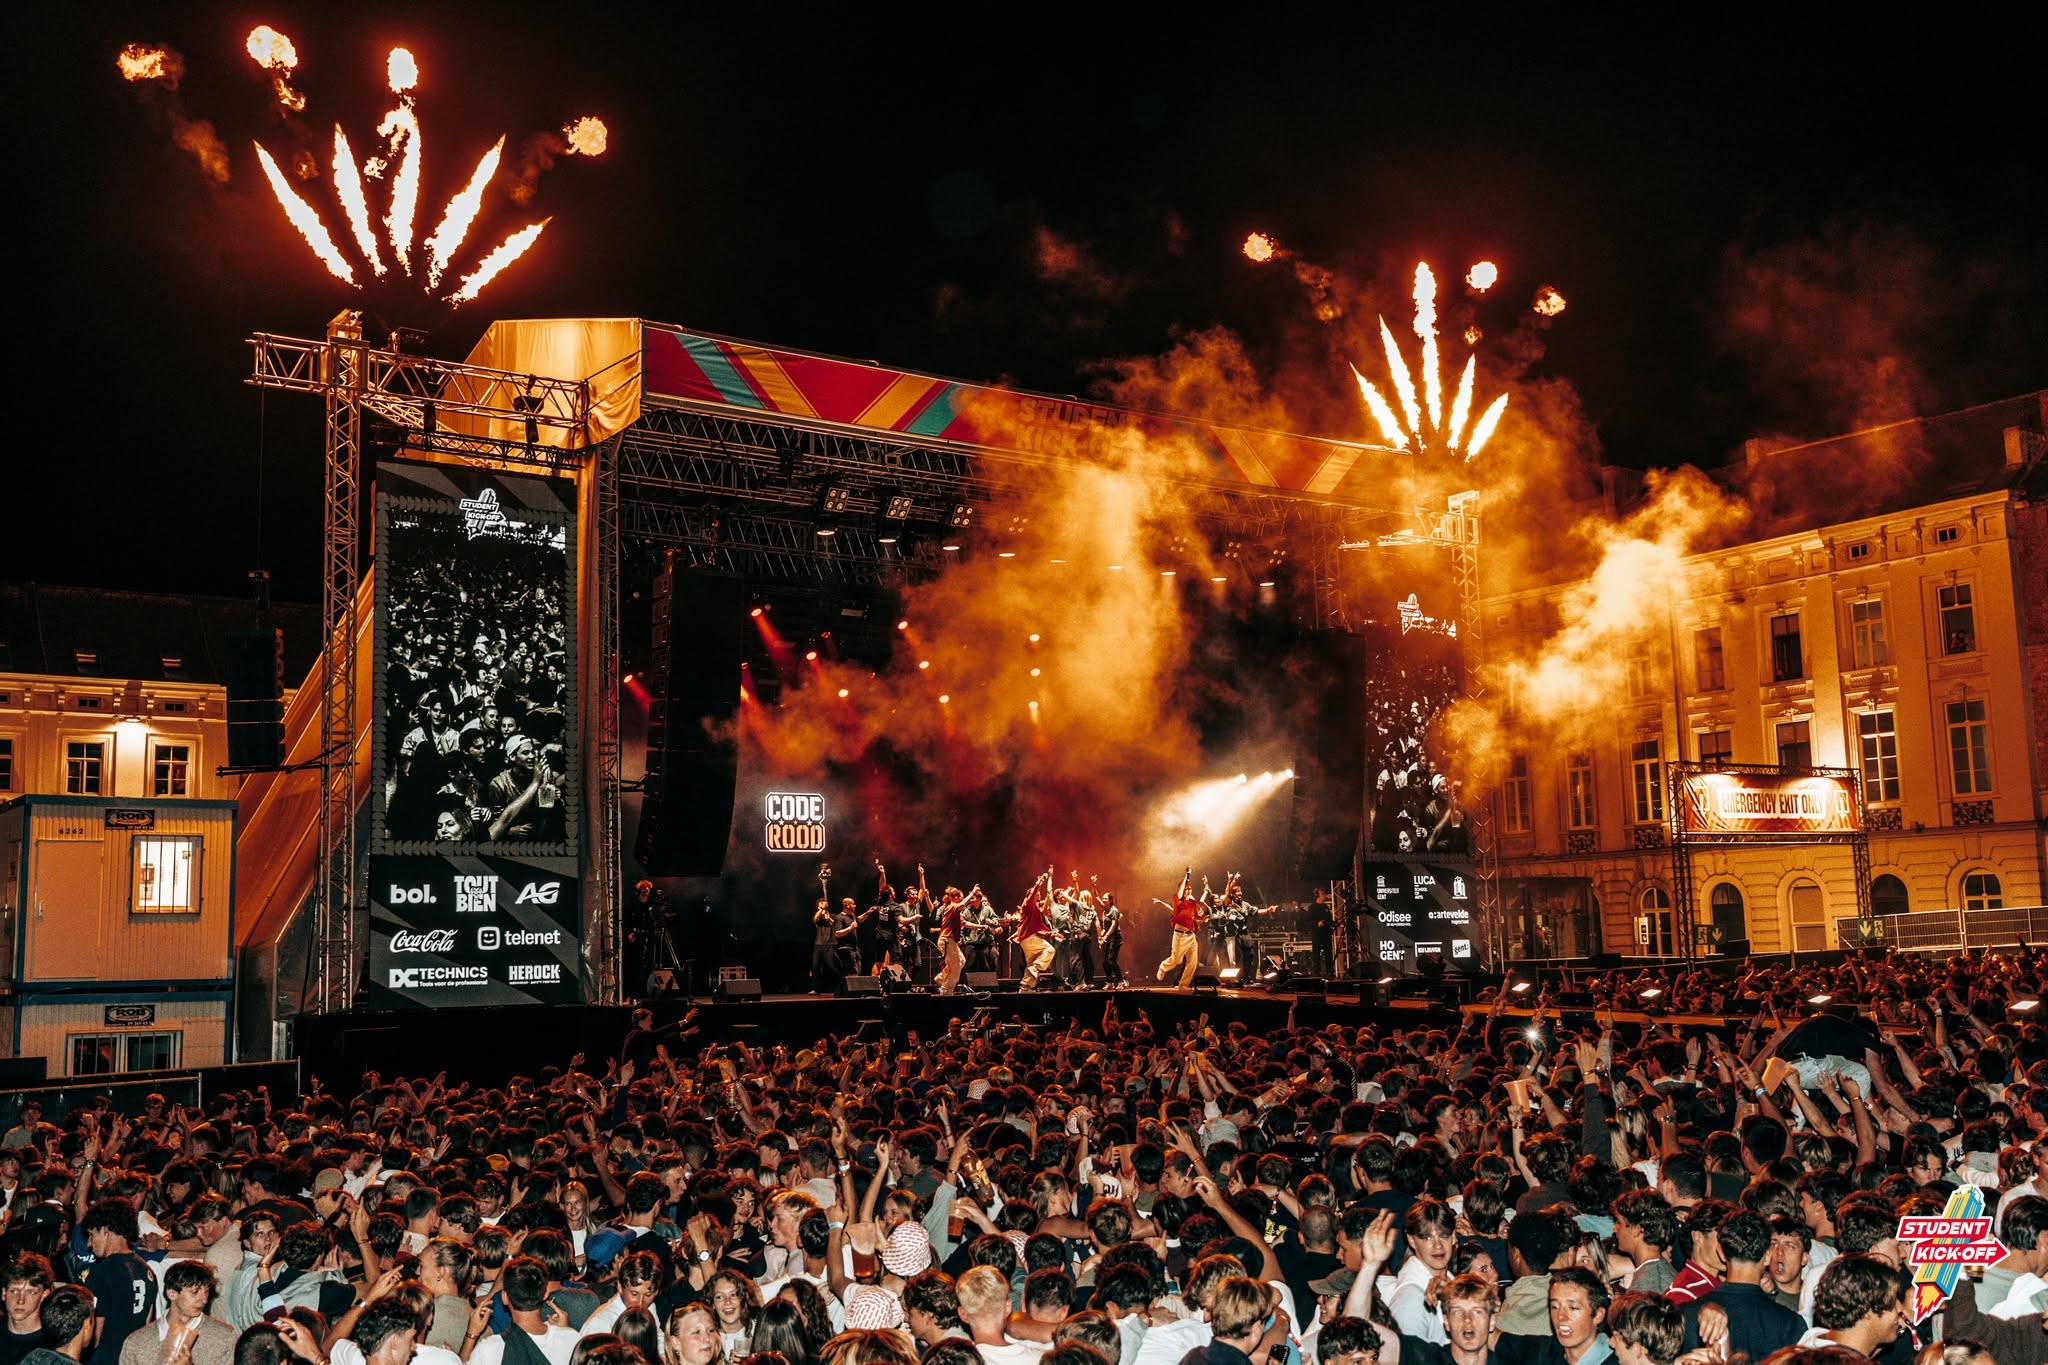
Also running on Beyond Ordering: Student Kick-off Gent, organised by Student Kick-Off vzw.
Checklist for the treasurer
- List every activity of your vzw: sport, bar, events, sponsoring, rental.
- Mark each one exempt, taxable or outside VAT, using the table above.
- Check whether your own work falls under article 44 before you count on the event exemption.
- Add up your taxable turnover excluding VAT and compare it with the small business threshold.
- Check the served food in your canteen against the GKS threshold.
- Give every activity its own price list and report.
- Agree the result with your accountant before the first event of the season.
Frequently asked questions
Must a vzw file VAT returns?
Periodic returns only under the normal scheme. Under the small business exemption it files an annual client listing instead. With only exempt work, neither.
Are sports clubs exempt from VAT?
Their sport for members is, when the club is non-profit and uses the receipts only to cover its costs. Their bar, shop and sponsor advertising aren't exempt by that rule.
Can a vzw recover VAT?
Only on purchases for its taxable activities, and only under the normal scheme. Exempt work and the small business exemption give no right to deduct.
Does a vzw have a VAT number?
Only when it makes taxable sales, or in some cases buys goods or services from another EU country. A vzw that only receives donations needs none.
Do I charge VAT when I invoice a vzw?
Usually, yes, as to any customer. There are two exceptions.
If you use the small business exemption yourself, you charge none. And for construction work for a vzw that files periodic VAT returns, the vzw pays the VAT itself (reverse charge). Ask your accountant in that case.
Split your activities before the next event
Write your vzw's activities on one sheet and give each a status. Then set up the canteen, the events and the crew credits as separate lists.
Want to see how that looks for your club? In a 30-minute demo we walk you through it. Does your association run its own bar or café? See our Bars & Clubs page. Rather ask a question first? Get in touch.
One price list and report per activity
In 30 minutes we'll show you how to keep your canteen, fundraiser and crew credits apart, so your accountant has each figure on its own.
Read more stories from our blog
Ordering via QR code in your bar or restaurant: how it works
Guests scan, order and pay upfront on their phone, and the order goes to the bar or kitchen. How it works, with the GKS rule and a summer bar.

Hospitality VAT in Belgium: which rate for your café or restaurant?
Hospitality VAT in Belgium: 12% on served food, 21% on every drink you serve, 6% on food and soft drinks to take away. With a worked bill.
How to organise a fuif: the bar, the till and no more drink tickets
Organise a fuif in five steps: registration, Unisono, the bar, reusable cups and a till with one queue instead of paper drink tickets.